
Flexible Financing for Damage Restoration in Everett
Water doesn’t wait for your savings account to catch up, and neither should you. Call us at (360) 502-8815 and we’ll walk you through payment options that let work start now without the stress of a single large outlay. At DryMark Restoration Everett, we’ve structured our billing around the reality that most homeowners in Snohomish County face these costs unexpectedly, often while juggling insurance adjusters, temporary housing, and the daily disruption of a damaged home.
Payment Options We Offer
Financing Plans for Larger Restoration Projects
For jobs where the scope extends beyond what immediate cash or insurance covers, we partner with established financing providers who specialize in home-improvement lending. These aren’t generic credit products; they’re structured around restoration timelines, with payment schedules that align to project milestones rather than demanding full repayment before your home is livable again. Most homeowners in Everett receive a decision within minutes during a brief phone conversation with our team. We don’t markup the financing; the rate you receive comes directly from the lender, and we document that clearly on your written scope under Haven Standard, Clause 1.
Major Credit Cards
We accept Visa, Mastercard, American Express, and Discover. This option works well for smaller mitigation jobs, deductible payments, or the gap between your insurance settlement and the full restoration cost. Many Everett homeowners use a card to secure immediate response while an adjuster reviews coverage, then pay the balance once the claim resolves. We process charges through a secure, PCI-compliant terminal; you’ll receive a detailed receipt matching your written scope line for line.
Cash and Personal Check
For homeowners who prefer to avoid financing altogether, we accept cash and personal check with no processing fees. Some clients in the Everett area choose this route when they’ve set aside emergency funds, received an insurance advance, or simply prefer the simplicity of a single transaction. Either way, Haven Standard, Clause 1 still applies: your written price is fixed before any work begins, and the final invoice matches it exactly unless you approve a documented change order in writing.
Up-Front Written Pricing, Every Time
This isn’t a payment method, but it’s the foundation that makes every payment method work. Before anyone enters your home, you receive a written scope with line-item costs for labor, equipment, materials, and any subcontracted trades. No verbal estimates that shift once demolition reveals hidden damage. We document what we find, photograph it, and price it transparently. If your financing application or insurance settlement takes a few days, your written price holds; we don’t charge holding fees or escalate costs while you arrange payment.
Simple Application Process
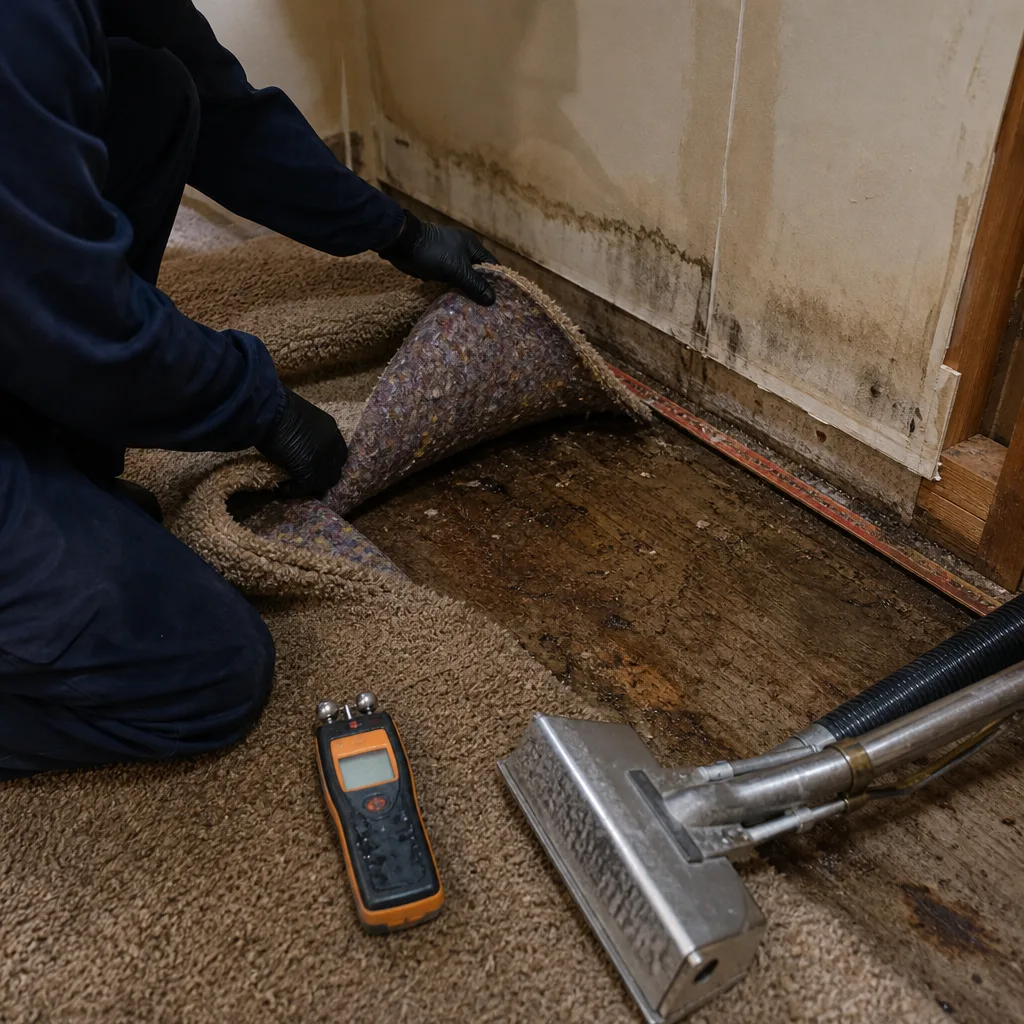
Step 1: Talk to us about your situation. When you call (360) 502-8815, a live person answers. We’ll ask about the damage, your insurance status, and whether you’re considering financing. There’s no scripted upsell; we’re gathering information so we can present relevant options. If you’re staring at standing water in your Silver Lake basement at 2 a.m., we handle the emergency dispatch first and discuss payment once the immediate threat is contained.
Step 2: Quick pre-qualification conversation. For financing, we’ll connect you with a lending specialist in a brief phone call. You’ll need basic information: income source, approximate credit range, and the project cost from your written scope. No hard credit pull for initial pre-qualification, no lengthy forms, and no obligation. Most callers know their options within ten minutes. We stay on the line if you want us to, or we step back if you prefer privacy.
Step 3: Choose your plan and schedule work. Once you select a payment approach, we confirm your start date and crew assignment. Financing paperwork, if applicable, is completed electronically before the team arrives. Your first payment typically aligns with project commencement or first draw, depending on the plan structure. Throughout the job, your daily photo record and moisture logs document progress, so both you and your lender have verification that funds are deploying against actual restoration work.
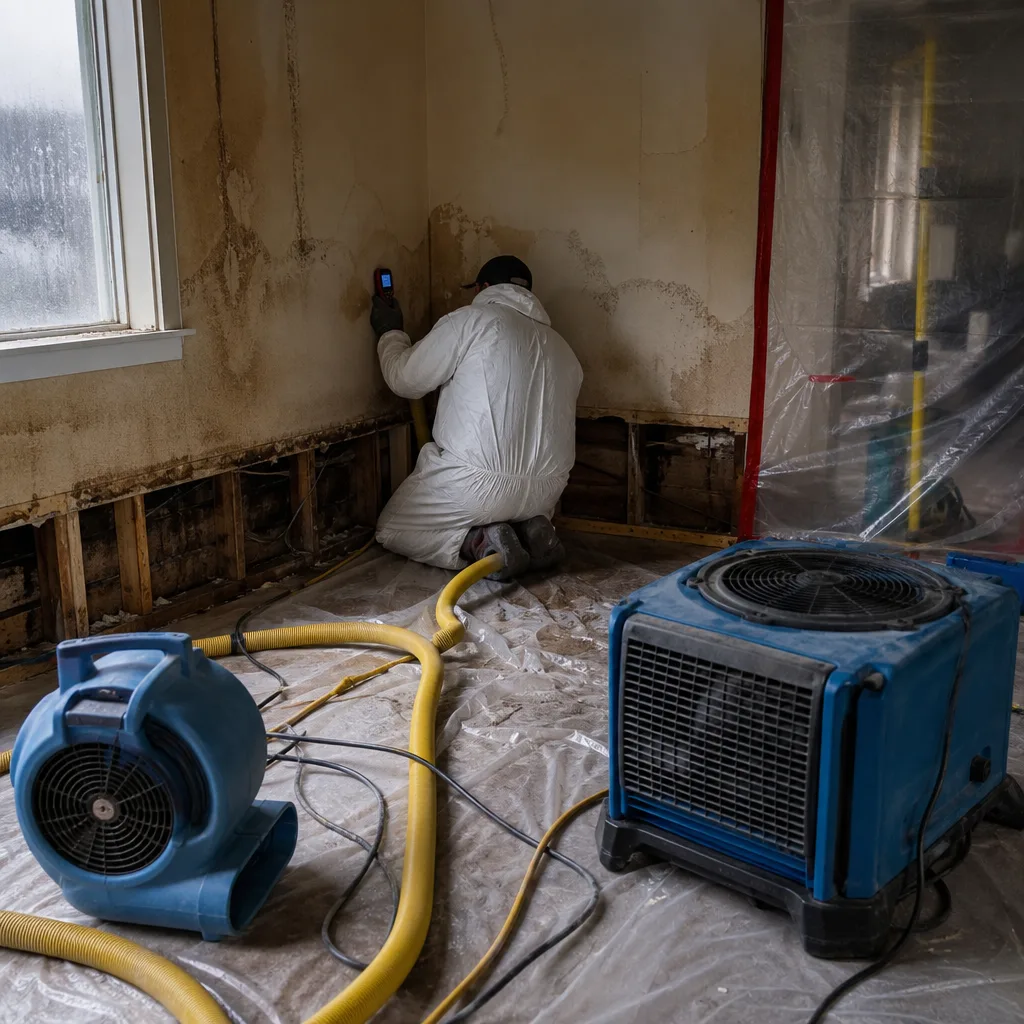 Before
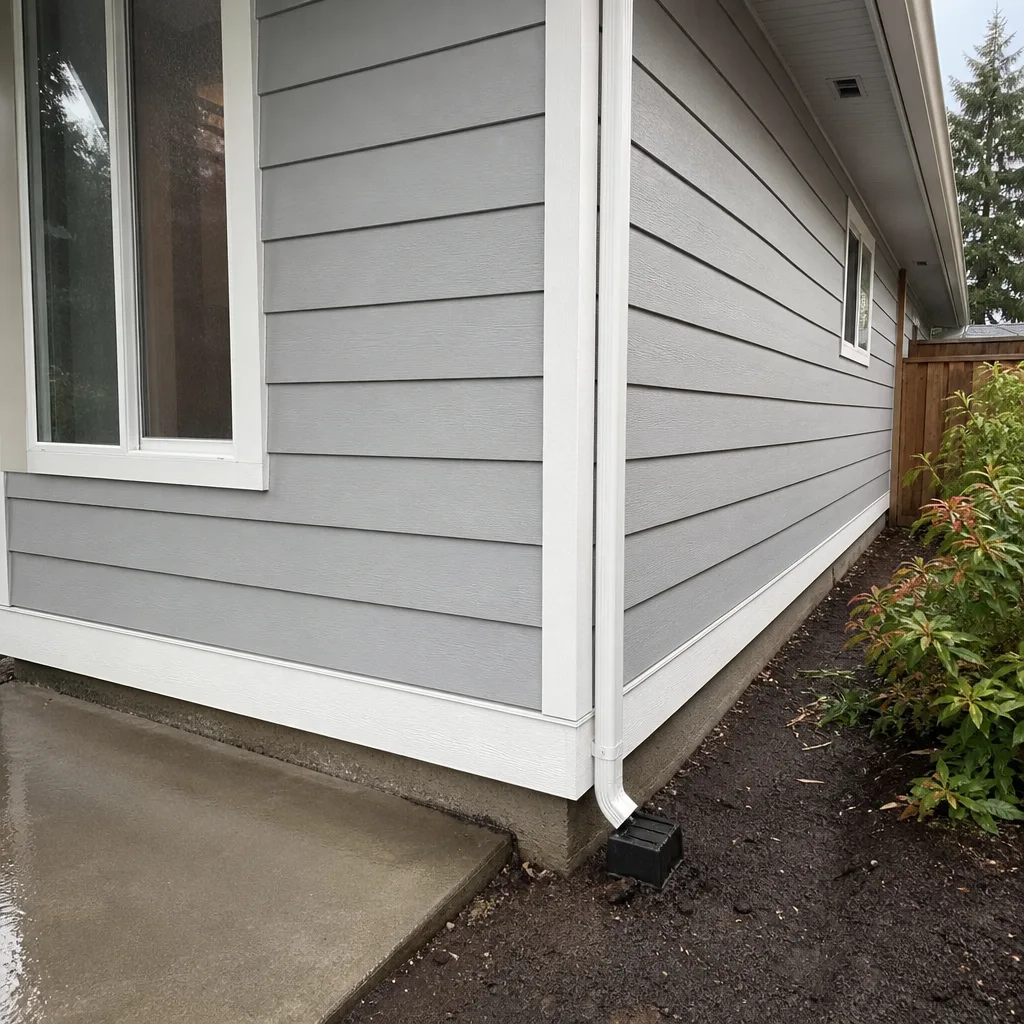 After
Frequently Asked Questions
Yes, we partner with home-improvement financing providers who offer installment plans for qualified homeowners. These plans cover everything from emergency water mitigation to full reconstruction, with payment schedules designed around project timelines rather than demanding upfront full payment. Call (360) 502-8815 to discuss your specific job scope and we’ll outline what options typically fit that range.
You’ll need a government-issued ID, proof of income, and the written scope we provide after assessing your damage. The lender may request additional documentation depending on your credit profile and the project size, but the initial pre-qualification conversation requires only basic information and involves no hard credit inquiry. We recommend having your insurance adjuster’s contact information ready as well, since many financed projects involve partial claim coverage that reduces the amount you need to borrow.
No, estimates are free. We assess the damage, document it with photographs, and deliver a written scope with line-item pricing at no charge. Haven Standard, Clause 1 guarantees that this written price is the price you’ll pay before work begins, with no hidden fees or post-arrival surcharges. Even if you choose not to proceed with us, you keep the written scope and photo documentation, which most insurance adjusters accept as credible damage evidence.
Yes, this is common. Many Everett homeowners receive an initial insurance advance that covers part of the restoration, then use financing for the deductible, code-upgrade requirements, or items excluded from coverage. We coordinate directly with your adjuster to document what’s claimable and what’s not, then structure your payment plan around the net amount you owe. Your written scope clearly separates insurance-billable items from out-of-pocket costs, so there’s no confusion about what financing needs to cover.
Standing water, mold spread, and structural damage don’t pause for financial convenience. At DryMark Restoration Everett, we’ve spent fourteen years building payment processes that remove that obstacle so work can start when it’s needed, not when the bank account is ready. Every option we offer operates under the same documentation standard: written price before work begins, photo record on every visit, and a 365-Day Done Right Promise backed by a signed guarantee. That’s Haven Standard, and it’s how we’ve restored over 12,000 homes since 2011.
Written by Alicia Brennan, Owner at DryMark Restoration Everett, serving Everett since 2011.